After-tax
After-tax refers to the net amount of income, investment yield, corporate profit, or cash flow retained after subtracting all mandatory statutory taxes.
What Does After-Tax Mean in Finance?
In economics, corporate accounting, and portfolio management, after-tax describes the net capital remaining once all applicable federal, state, local, and cross-border tax liabilities have been deducted from gross financial receipts. Whether evaluating an individual salary, a corporate income statement, or the dividend yield of a stock portfolio, pre-tax metrics represent theoretical earnings, whereas after-tax metrics establish real, spendable purchasing power.
Failing to account for after-tax realities leads to severe capital misallocations. Two investment opportunities displaying identical 8.0% nominal pre-tax yields can deliver radically divergent wealth outcomes depending on whether the proceeds are taxed as ordinary income, qualified dividends, long-term capital gains, or shielded under statutory exemptions.
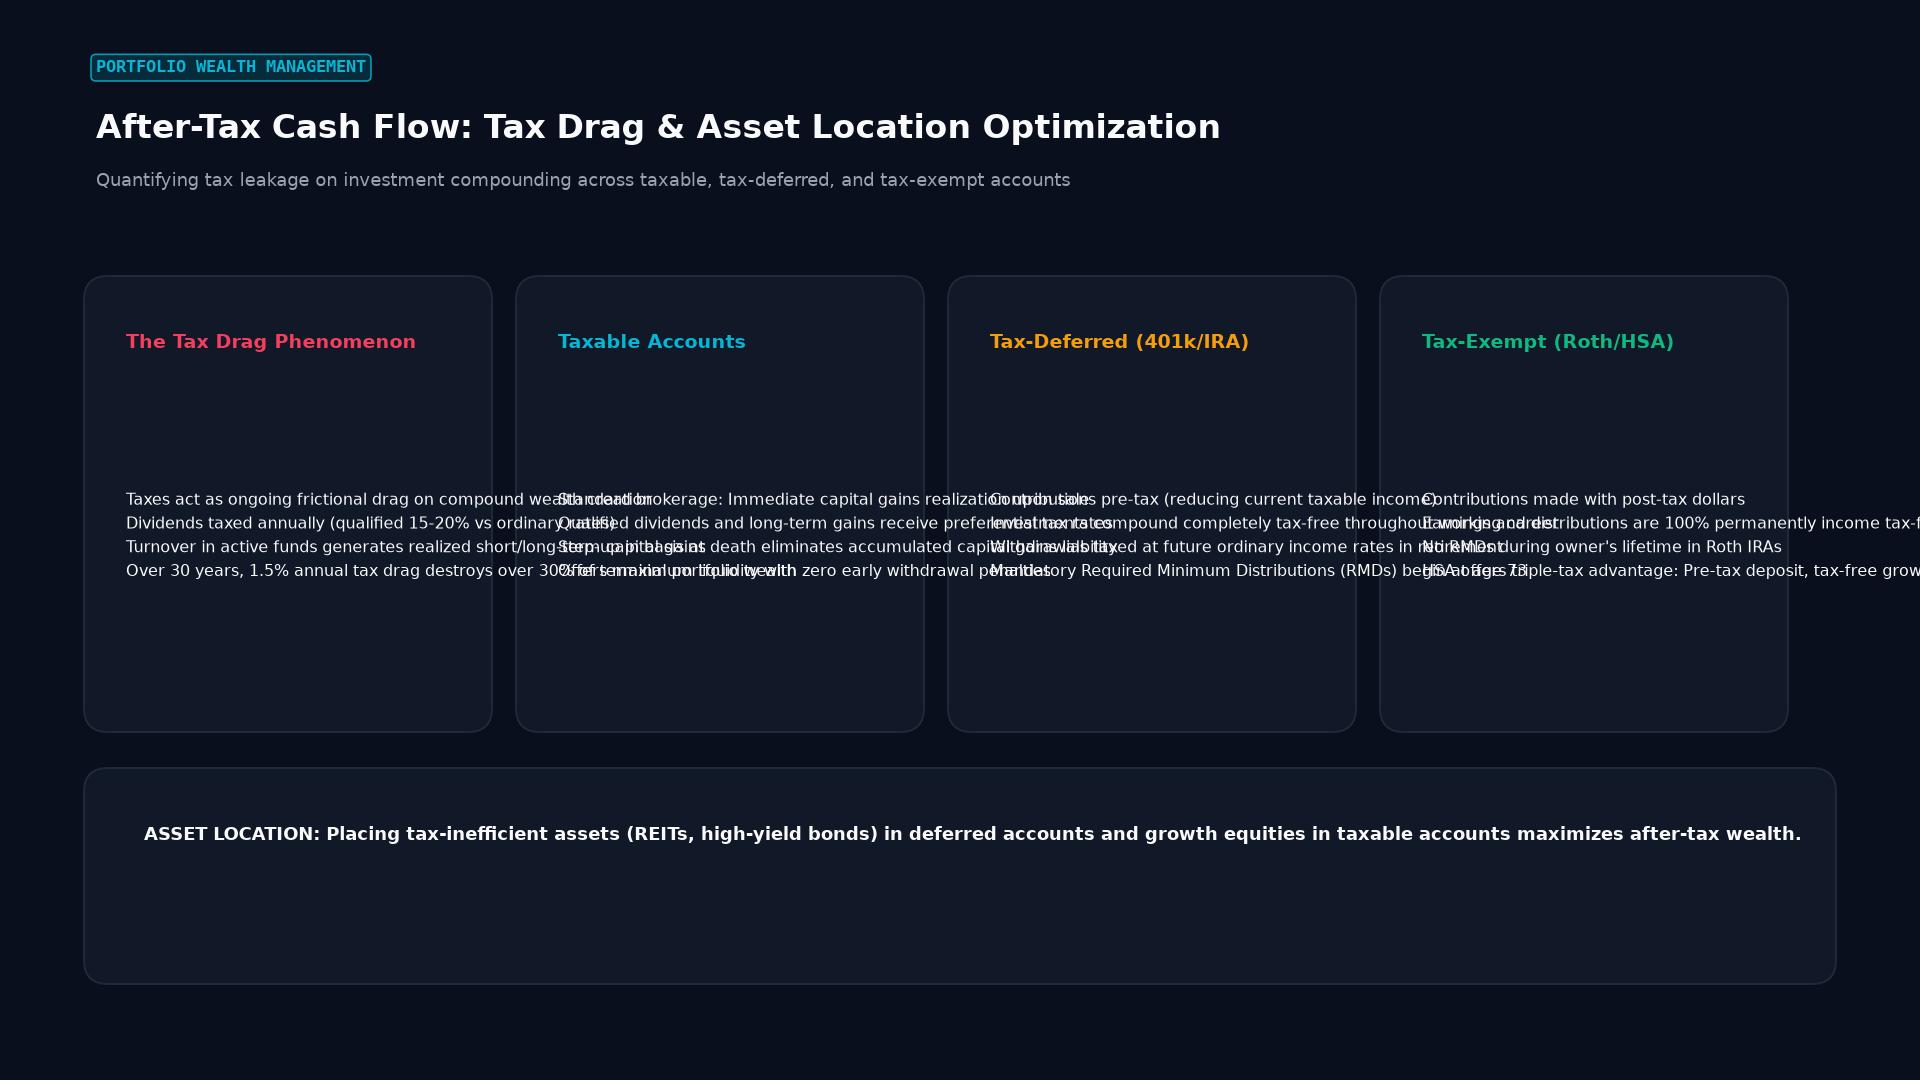 Figure: Quantifying tax leakage on investment compounding across taxable, tax-deferred, and tax-exempt accounts
Macroeconomics: Disposable Personal Income (DPI)
At the macroeconomic level, central banks and treasury departments track after-tax personal receipts via Disposable Personal Income (DPI), published by the US Bureau of Economic Analysis (BEA):
$$\text{Disposable Personal Income} = \text{Personal Gross Income} - \text{Personal Current Taxes}$$
Because consumer spending constitutes roughly 70% of total economic activity in developed economies, DPI is the primary driver of household consumption, personal savings rates, and retail sales volume.
When national governments enact fiscal stimulus (such as tax rebates or lower payroll withholding), after-tax disposable income expands immediately. This expansion stimulates consumer demand, influences corporate earnings forecasts, and prompts foreign exchange traders to bid up the domestic currency in anticipation of higher policy interest rates from central banks.
Macro Transmission of After-Tax Income to Currency Markets:
┌────────────────────────┐
│ Federal Tax Reform     │
│ Lowers Effective Rates │
└───────────┬────────────┘
            │
            ▼
┌────────────────────────┐
│ Disposable Personal    │
│ Income (DPI) Expands   │
└───────────┬────────────┘
            │
            ▼
┌────────────────────────┐
│ Consumer Spending &    │
│ Retail Velocity Rise   │
└───────────┬────────────┘
            │
            ▼
┌────────────────────────┐
│ Central Bank Hikes     │
│ Rates to Anchor Demand │
└───────────┬────────────┘
            │
            ▼
┌────────────────────────┐
│ Domestic Currency (FX) │
│ Appreciates Globally   │
└────────────────────────┘
Corporate Finance: From Operating Revenue to After-Tax Net Income
Corporate financial controllers monitor the transition from top-line revenue to bottom-line after-tax profit using structured income statement tiers:
| Income Statement Tier | Financial Definition | Analytical Significance |
|---|---|---|
| Gross Operating Profit | Revenue minus Cost of Goods Sold (COGS) | Core manufacturing efficiency and pricing power |
| Operating Income (EBIT) | Gross Profit minus Operating Expenses (SG&A) | Core operational profitability before capital structure |
| Pre-Tax Income (EBT) | Operating Income minus Interest Expense | Net earnings exposed to statutory corporate tax rates |
| Net Income (EAT) | Pre-Tax Income minus Corporate Taxes | True after-tax profit available for dividends or reinvestment |
In corporate valuation, analysts calculate Net Operating Profit After Tax (NOPAT):
$$\text{NOPAT} = \text{EBIT} \times (1 - T_c)$$
Where $T_c$ is the effective corporate tax rate. NOPAT isolates an enterprise’s true after-tax operating capability without distortions caused by differing debt financing leverage.
Portfolio Strategy: The Real After-Tax Return Formula
To preserve wealth, an investor must evaluate returns against both taxation and price inflation. The Real After-Tax Return formula quantifies this relationship:
$$\text{Real After-Tax Return} = [R_{\text{nominal}} \times (1 - t)] - i$$
Where:
- $R_{\text{nominal}}$ = Nominal investment return or interest coupon
- $t$ = Marginal combined income tax rate
- $i$ = Annual inflation rate
Numerical Case Study: The Inflation and Tax Trap
Consider an investor earning a 7.0% nominal return on corporate bonds during a period when the annual inflation rate ($i$) is 4.0%, and their marginal combined tax rate ($t$) is 35%:
$$\text{After-Tax Nominal Return} = 7.0% \times (1 - 0.35) = 4.55%$$
$$\text{Real After-Tax Return} = 4.55% - 4.00% = +0.55%$$
Although the pre-tax headline yield appeared substantial at 7.0%, the investor’s real purchasing power increased by a mere 55 basis points. If nominal returns had been 5.0%, the real after-tax return would have turned negative ($-0.75%$), quietly eroding the investor’s real capital despite positive nominal accounting gains.
Key Takeaways
- After-tax represents the actual net cash flow, profit, or income retained after all mandatory government tax liabilities have been satisfied.
- Disposable Personal Income (DPI) tracks after-tax household capital, serving as a primary leading indicator for consumer spending and GDP growth.
- Corporate finance uses Net Operating Profit After Tax (NOPAT) to evaluate pure operating profitability independent of capital debt structure.
- Wealth preservation requires calculating real after-tax returns, accounting for both marginal tax liabilities and purchasing-power inflation.
Frequently Asked Questions
What is the difference between statutory and effective after-tax rates?
The statutory tax rate is the official percentage set by law for a specific tax bracket. The effective after-tax rate is the actual percentage of total income paid in taxes after utilizing deductions, tax credits, depreciation allowances, and exemptions.
Why do municipal bonds trade at lower pre-tax yields than corporate bonds?
Municipal bonds are exempt from federal income taxes (and often state taxes). Because investors evaluate returns on an after-tax basis, high-income earners accept a lower pre-tax yield on municipal debt, knowing they retain 100% of the coupon payment without tax deductions.
How do capital gains tax rates impact after-tax returns?
In many jurisdictions, assets held for more than one year qualify for long-term capital gains tax rates (typically 0%, 15%, or 20% in the United States), which are significantly lower than ordinary income tax rates (which reach up to 37%). This differential substantially boosts the after-tax return of long-term buy-and-hold equity strategies.
Ready to trade forex?
Open a free demo account with a regulated broker. Practice with virtual funds before risking real money.