Against the box
Selling short against the box is a trading strategy where an investor simultaneously holds a long position and sells short an identical number of shares of the same stock to lock in paper gains without immediately liquidating the underlying asset.
What Does “Against the Box” Mean in Trading?
“Against the box” (commonly referred to as selling short against the box) is an equity trading and hedging technique where an investor who already owns shares of a public company borrows and sells short the exact same quantity of shares of that company.
The terminology traces back to the era of physical securities handling, when paper stock certificates were held under custody in a brokerage firm’s safe-deposit box (colloquially called “the box”). If an investor instructed their broker to execute a short sale while their original share certificates remained untouched inside the safe, the investor was said to be selling short “against the box.”
By holding both a long position and an identical short position concurrently, the investor creates a market-neutral position (a delta of zero). The net portfolio value becomes completely insulated from future share price fluctuations:
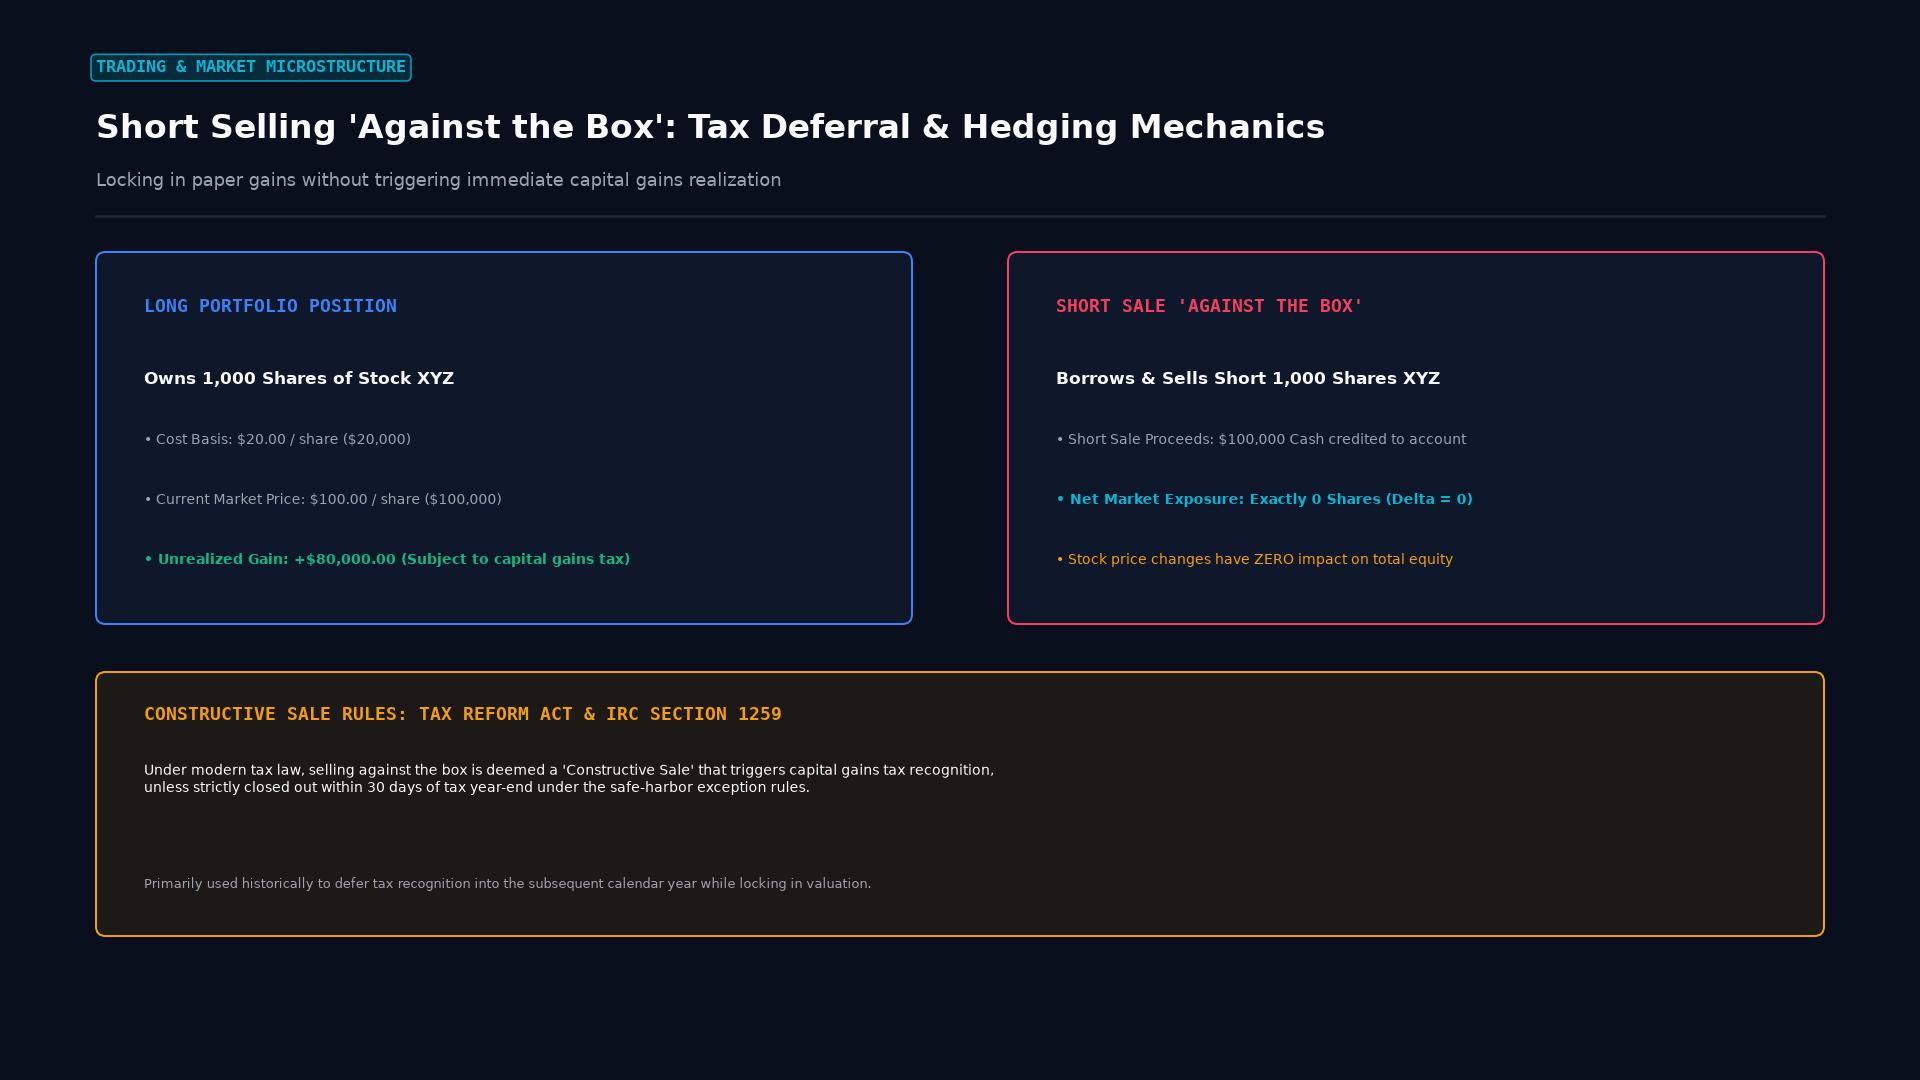 Figure: Hedging paper gains via synthetic delta-neutral shorting: neutralizing price volatility on long stock holdings while navigating IRS Section 1259 constructive sale rules.
Historical Motivation: Tax Deferral Prior to 1997
Before 1997, selling short against the box was among the most popular tax-avoidance strategies utilized by wealthy corporate insiders and hedge fund founders:
- Locking In Profits: Suppose an investor bought tech shares for $100,000 that appreciated to $5,000,000. Liquidating the shares in November would trigger an immediate, massive capital gains tax bill due in April of the following year.
- Tax Year Arbitrage: By selling short against the box at $5,000,000, the investor locked in the $4,900,000 gain in November without triggering a taxable event. The investor received 95% of the short sale proceeds in cash via a margin loan.
- Delayed Delivery: In January of the subsequent tax year, the investor delivered their original long shares to cover the short sale, effectively postponing tax liability into the next calendar tax cycle.
Regulatory Crackdown: IRC Section 1259 Constructive Sales
The widespread use of this strategy by high-profile executives prompted the United States Congress to enact the Taxpayer Relief Act of 1997, introducing Section 1259 of the Internal Revenue Code (IRC § 1259), known as the Constructive Sales Rule:
- The Statutory Rule: Under IRC § 1259, if an investor holds an appreciated financial position and enters into an offsetting transaction (such as a short sale against the box, a total return swap, or a forward sale contract) that substantially eliminates both risk of loss and opportunity for gain, the transaction is legally deemed a constructive sale.
- Immediate Taxation: The investor must recognize capital gains on the appreciated long position immediately, treating the asset as if it were sold at its fair market value on the day the short position was opened.
IRC § 1259 Constructive Sale Legal Trigger:
┌────────────────────────────────────────────────────────┐
│ Investor Holds Appreciated Stock (Large Paper Gain)    │
└──────────────────────────┬─────────────────────────────┘
                           │
                           ▼ Executes Offsetting Short
┌────────────────────────────────────────────────────────┐
│ IRS Constructive Sale Triggered Under IRC § 1259       │
└──────────────────────────┬─────────────────────────────┘
                           │
                           ▼
┌────────────────────────────────────────────────────────┐
│ Unrealized Paper Gain Instantly Recognized for Taxes   │
│ Tax liability triggered immediately; deferral negated  │
└────────────────────────────────────────────────────────┘
The 30-Day Safe Harbor Exception
The tax code provides a narrow exception under IRC § 1259(c)(3) allowing short-term hedges across year-end, provided all three conditions are satisfied:
- The short position is closed on or before the 30th day following the close of the taxable year (typically by January 30).
- The taxpayer holds the appreciated long position unhedged for at least 60 days following the closing of the short sale.
- The long position is not subjected to other risk-reducing derivative contracts during that 60-day unhedged window.
Corporate Governance and Insider Trading Restrictions
Beyond general tax law, corporate executives and company directors face strict prohibitions regarding selling against the box:
- Section 16(c) of the Securities Exchange Act of 1934: Prohibits corporate officers, directors, and beneficial owners of more than 10% of any class of equity security from executing any direct short sales or short sales against the box in their company’s stock.
- Corporate Insider Trading Policies: Modern public companies explicitly forbid employees from hedging company stock through short sales, zero-cost collars, or prepaid forward contracts, ensuring insider economic interests remain aligned with public shareholders.
Key Takeaways
- Selling short against the box involves borrowing and shorting the exact number of shares an investor already owns, eliminating all price risk.
- Historically used to lock in paper profits and push capital gains tax liabilities into subsequent tax years.
- The Taxpayer Relief Act of 1997 created the Constructive Sales Rule (IRC § 1259), treating the transaction as an immediate taxable liquidation.
- Corporate insiders are legally barred from shorting their company’s stock against the box under Section 16(c) of the Securities Exchange Act.
Frequently Asked Questions
Can an investor still sell short against the box today?
Yes, an investor can technically execute the trade through a brokerage margin account, but it no longer accomplishes tax deferral. The moment the short sale is executed, the IRS treats the long position as sold under constructive sales rules, triggering immediate capital gains taxes.
What are modern alternatives to selling short against the box?
Institutional investors seeking to hedge concentrated equity positions without triggering constructive sales often use zero-cost collars with wide out-of-the-money bands, exchange funds (which swap single-stock risk for a diversified private partnership fund), or charitable remainder trusts (CRTs).
How does selling short against the box affect dividend payments?
Because the investor is both long and short identical share amounts, the dividend mechanics cancel out. The investor receives dividend payments on the long shares held in the box, but must simultaneously pay an identical substitute dividend payment to the lender of the borrowed short shares.
Ready to trade forex?
Open a free demo account with a regulated broker. Practice with virtual funds before risking real money.