AHCU
AHCU stands for American Healthcare Credit Union, a member-owned, federally insured cooperative financial institution delivering specialized banking, mortgage, and commercial practice financing to the healthcare sector.
What Does AHCU Stand For in Banking and Credit Unions?
In retail banking, cooperative finance, and institutional lending, AHCU stands for American Healthcare Credit Union (as well as regional variants such as Associated Healthcare Credit Union). It designates a specialized, member-owned financial cooperative established to provide comprehensive depository services, consumer credit, residential mortgages, and commercial healthcare practice financing to medical professionals, hospital networks, research facilities, and their families.
Operating as a not-for-profit cooperative financial institution, AHCU is chartered under federal or state credit union statutes. Unlike investor-owned commercial banks that operate to maximize quarterly profits and dividends for external equity shareholders, AHCU returns its operating net earnings directly to its member-depositors through lower interest rates on loans, reduced transaction fees, and higher annual percentage yields (APY) on savings and certificate accounts.
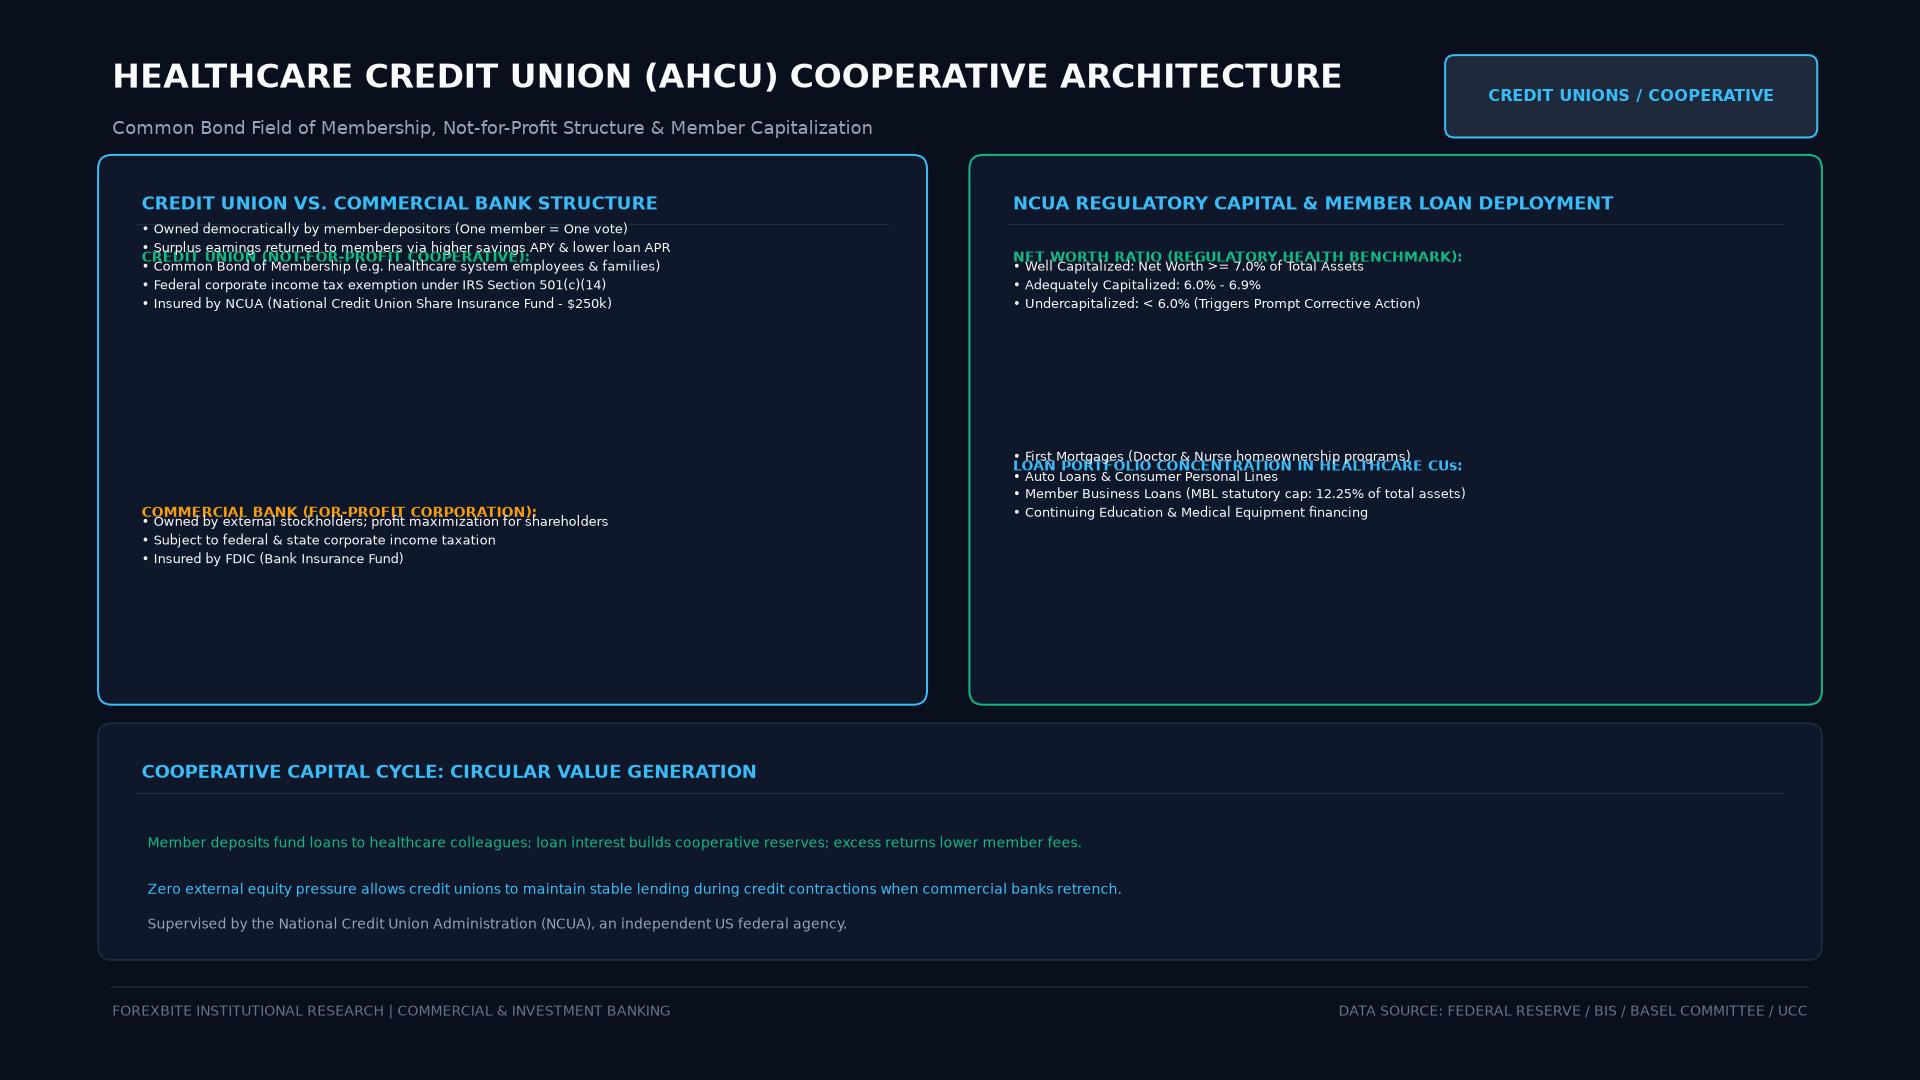 Figure: Union institutional liquidity management, payroll deduction clearing, welfare benefit trust reserves, and member credit union affiliations.
Regulatory Oversight and Federal Deposit Insurance
Like all federally insured credit unions in the United States, AHCU operations are regulated and insured by the National Credit Union Administration (NCUA), an independent federal agency created by the US Congress:
- National Credit Union Share Insurance Fund (NCUSIF): Member deposits (known as “shares” in credit union terminology) are backed by the NCUSIF. This federal insurance guarantees depositor balances up to $250,000 per individual depositor, carrying the identical full faith and credit backing of the United States government as the Federal Deposit Insurance Corporation (FDIC) provides for commercial banks.
- Capital Adequacy Standards: The NCUA enforces strict Prompt Corrective Action (PCA) rules, requiring credit unions to maintain a net worth ratio of at least 7.0% relative to total assets to be classified as “well-capitalized.”
- Field of Membership (FOM) Charter: Under the Federal Credit Union Act, credit unions operate under a designated common bond. AHCU maintains an occupational and associational charter serving employees, medical students, nursing staff, clinical contractors, and affiliated entities across participating hospital healthcare systems.
Federal Regulatory & Insurance Framework:
┌────────────────────────────────────────────────────────┐
│ United States Federal Government (Full Faith & Credit) │
└──────────────────────────┬─────────────────────────────┘
                           │
             ┌─────────────┴─────────────┐
             ▼                           ▼
 ┌───────────────────────┐   ┌───────────────────────────┐
 │ FDIC Insurance Fund   │   │ NCUSIF Insurance Fund     │
 │ (Commercial Banks)    │   │ (Credit Unions / AHCU)    │
 ├───────────────────────┤   ├───────────────────────────┤
 │ • Covers checking,    │   │ • Covers share draft,     │
 │   savings, CDs        │   │   share savings, share CDs│
 │ • $250,000 per account│   │ • $250,000 per member     │
 └───────────────────────┘   └───────────────────────────┘
Specialized Financial Products for Healthcare Professionals
Because healthcare workers experience unique career trajectories characterized by extensive educational debt followed by high, stable earning power, AHCU tailors its underwriting protocols to accommodate these balance sheet dynamics:
| Financial Product | Underwriting Customization | Market Advantage for Borrowers |
|---|---|---|
| Physician & Resident Mortgages | Student loan debt excluded from DTI ratios | Up to 100% financing with zero Private Mortgage Insurance (PMI) |
| Relocation & Residency Loans | Underwritten using future medical employment contracts | Unsecured working capital for moving and licensing expenses |
| Medical Practice Acquisition | Cash-flow underwriting based on patient volumes | Term loans to purchase clinical equipment and real estate |
| Healthcare Student Loan Refinancing | Tiered interest rate discounts for affiliated health systems | Consolidates federal and private debt into single low fixed rate |
In a traditional commercial bank, an early-career medical resident earning a modest training stipend while carrying $250,000 in medical school student loans would be rejected for a home mortgage due to rigid Debt-to-Income (DTI) caps. Specialized institutions like AHCU utilize modified underwriting matrices, recognizing that the resident’s future board certification and guaranteed surgical income minimize long-term credit risk.
Commercial Practice Financing and Equipment Leasing
Beyond individual consumer accounts, healthcare credit unions fund medical infrastructure:
- Diagnostic Equipment Lines: Structuring asset-based loans and equipment leases for magnetic resonance imaging (MRI) units, surgical robotics, and computed tomography (CT) scanners.
- Medical Working Capital Facilities: Extending revolving credit lines secured by medical accounts receivable and insurance clearing reimbursements from government programs (Medicare and Medicaid) and private health maintenance organizations.
Key Takeaways
- AHCU stands for American Healthcare Credit Union, a member-owned cooperative financial institution serving medical and health sector workers.
- Member share deposits are federally insured up to $250,000 by the National Credit Union Share Insurance Fund (NCUSIF), backed by the US government.
- As not-for-profit cooperatives under IRC § 501(c)(14), credit unions return earnings to members via lower loan rates and higher deposit yields.
- AHCU provides specialized underwriting for healthcare professionals, including physician home loans with zero PMI and practice acquisition credit.
Frequently Asked Questions
Are deposits at AHCU as safe as deposits at a commercial bank?
Yes. Deposits at federally insured credit unions are backed by the National Credit Union Share Insurance Fund (NCUSIF). The NCUSIF provides the exact same $250,000 statutory federal deposit guarantee backed by the full faith and credit of the United States government as the FDIC provides for commercial banks.
Who is eligible to join AHCU?
Membership eligibility is governed by the credit union’s Field of Membership charter. Typically, anyone employed by an affiliated hospital network, medical clinic, pharmaceutical company, or healthcare association, as well as their immediate family and household members, is eligible to open an account.
Why do credit unions call deposits “shares”?
Because credit unions are financial cooperatives, depositing money purchases an ownership share in the institution. Rather than being a mere customer, each depositor is a member-owner with the democratic right to vote for the credit union’s volunteer Board of Directors.
Ready to trade forex?
Open a free demo account with a regulated broker. Practice with virtual funds before risking real money.