Day Loan (Morning Loan)
A day loan (or morning loan) is an uncollateralized, intraday credit facility extended by a commercial bank to a securities broker-dealer to finance the purchase and receipt of securities before they can be pledged as collateral for overnight margin financing.
What Is a Day Loan?
In commercial banking and institutional securities clearing, a day loan (historically termed a morning loan) is a specialized, uncollateralized intraday credit line extended by a commercial clearing bank to a securities broker-dealer.
The day loan was created to resolve a fundamental operational timing conflict in securities settlement:
- The Delivery Squeeze: In the morning (typically around 09:00 AM), a brokerage firm must wire cash to clearing houses (such as the Depository Trust & Clearing Corporation - DTCC) to accept delivery of newly purchased shares on behalf of institutional and retail margin clients.
- The Collateral Dilemma: Under standard banking rules, a broker funds these purchases through collateralized call loans. However, the broker cannot legally pledge the shares as collateral until it actually receives them from the clearing house.
To bridge this several-hour liquidity gap, the commercial bank grants an uncollateralized day loan in the morning. Once the securities are physically or electronically credited to the broker’s custodial depository account in the afternoon, the broker pledges the securities to the bank, transforming the unsecured day loan into a fully secured overnight broker call loan before the close of business.
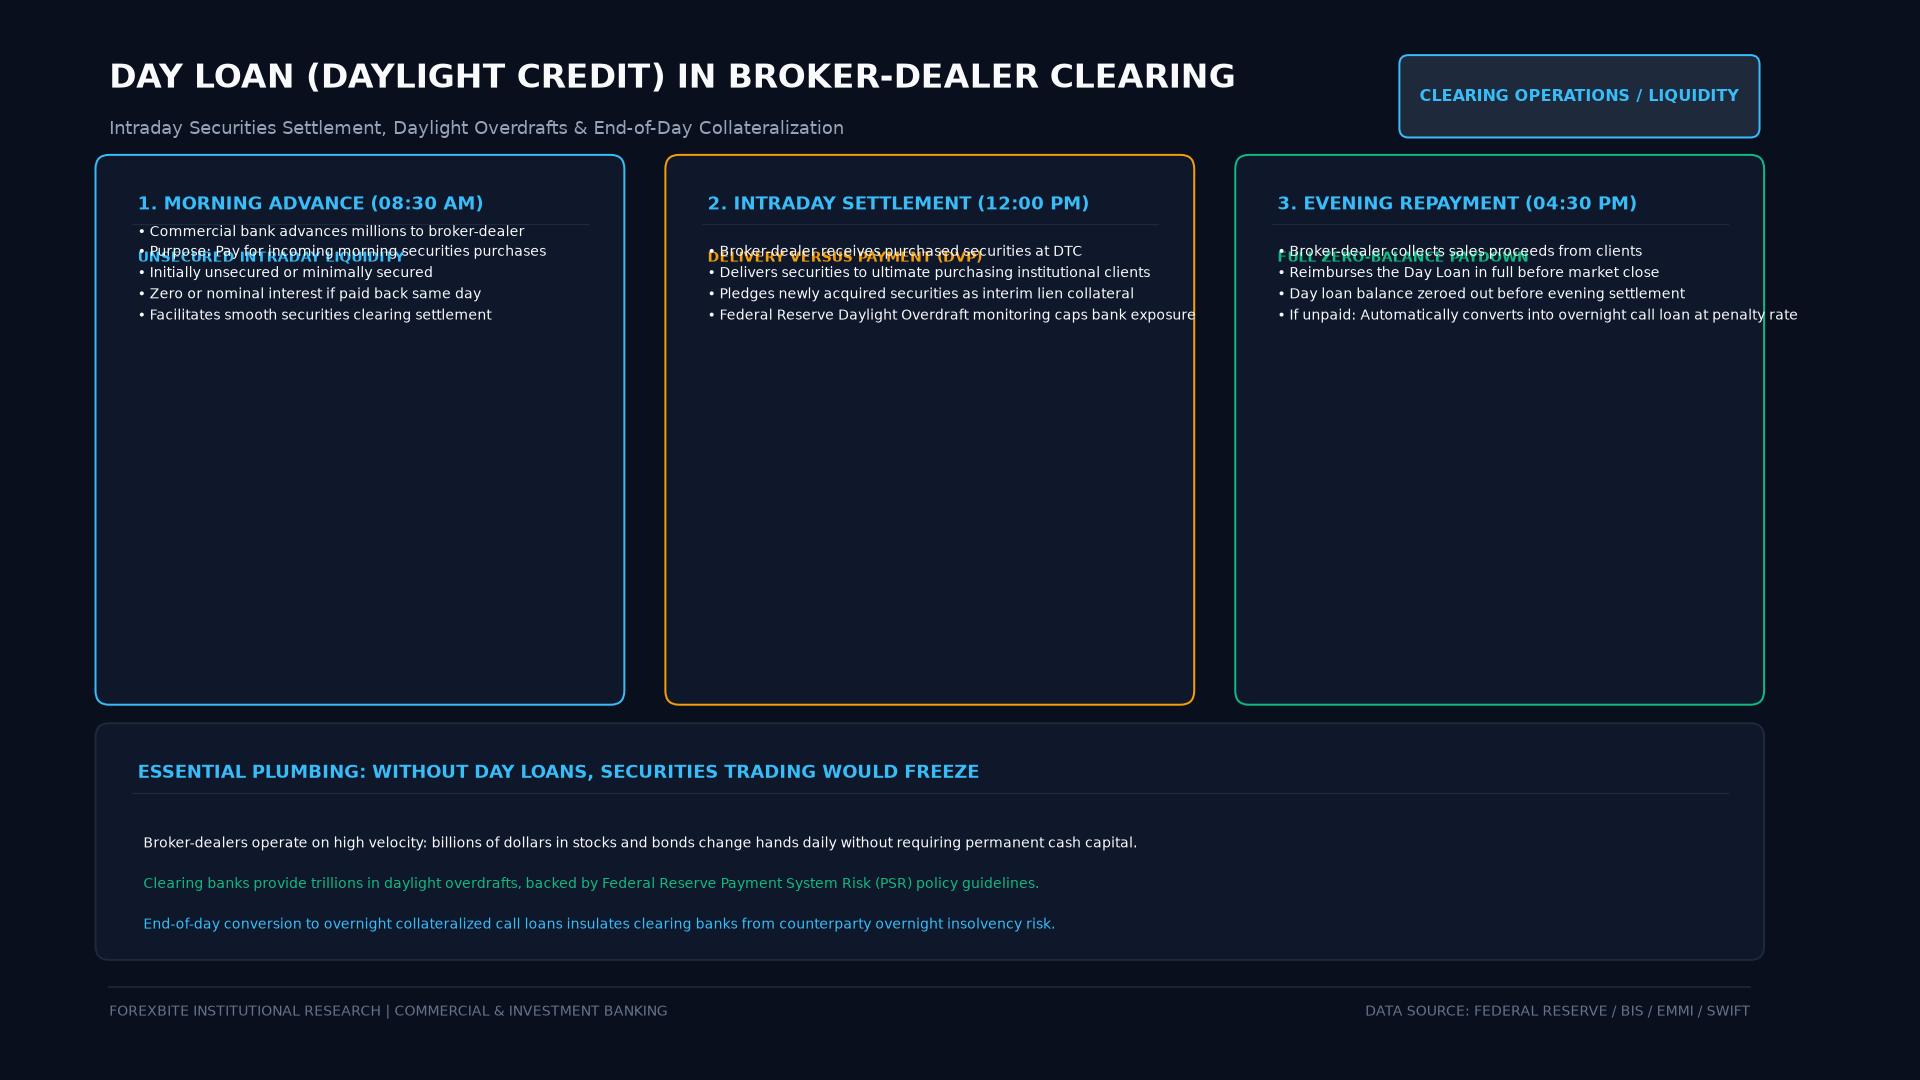 Figure: Specialized broker-dealer daylight liquidity facility: intraday underwriting, securities settlement clearing, and mandatory end-of-day payoff.
Technical Mechanics & Intraday Liquidity Pricing
Because day loans are active for only 6 to 8 hours during daytime bank business hours, they are not priced using standard annual interest calculations. Instead, banks charge an intraday facility fee or track exposure through Daylight Overdraft limits.
Federal Reserve Daylight Overdraft Formulation
Under the Federal Reserve’s Policy on Payment System Risk (PSR), depository institutions accessing intraday credit across the Fedwire network incur daylight overdraft charges:
$$\text{Daylight Overdraft Fee} = \text{Average Daily Uncollateralized Overdraft} \times \left( \frac{\text{Annualized Fee Rate}}{360} \right) \times \left( \frac{\text{Operating Hours}}{24} \right)$$
Where the Fed assesses an effective fee rate (historically 50 basis points annualized) on uncollateralized intraday overdrafts that exceed a bank’s capital net debit cap.
Day Loan Conversion Equation
At the conclusion of the trading day, the day loan balance ($L_{\text{day}}$) must be extinguished:
$$L_{\text{day}} - \text{Cash Repayment} - L_{\text{call_converted}} = 0$$
Where $L_{\text{call_converted}}$ is backed by eligible collateral subject to regulatory margin requirements:
$$\text{Pledged Collateral Market Value} \ge \frac{L_{\text{call_converted}}}{1 - \text{Haircut}}$$
Comparative Matrix: Institutional Credit Facilities
| Credit Facility | Duration | Collateral Required? | Conversion Mechanism | Primary Risk |
|---|---|---|---|---|
| Day Loan (Morning Loan) | Intraday (6 to 8 hours) | Uncollateralized | Converted to Call Loan at market close | Intraday broker insolvency |
| Broker Call Loan | Overnight / On Demand | Fully Collateralized (Stocks/Bonds) | Rolled over daily on demand | Asset collateral price drop |
| Repo Agreement | Overnight to Months | Fully Collateralized (Treasuries) | Title transfer with forward buyback | Counterparty repo default |
| Daylight Overdraft | Minutes to Hours | Uncollateralized or Collateralized | Cleared by end of Fedwire window | Central bank systemic gridlock |
Real-World Case Study: The 1884 Wall Street Crash & The Grant & Ward Scandal
The systemic danger of uncollateralized day loans was demonstrated in May 1884 during the collapse of the Wall Street brokerage firm Grant & Ward (co-founded by former US President Ulysses S. Grant and financier Ferdinand Ward).
Anatomy of an Unsecured Day Loan Disaster:
1. The Fraud: Ferdinand Ward operated an elaborate Ponzi scheme, pretending to hold lucrative federal government supply contracts.
2. The Mechanism: Every morning, Marine National Bank of New York extended massive, uncollateralized day loans to Grant & Ward to finance purported securities purchases.
3. The Abuse: Instead of using the day loans to buy legitimate shares that would be pledged by evening, Ward diverted the morning bank funds to pay off prior debts and finance fraudulent speculative bets.
4. The Collapse (May 6, 1884): When Marine National Bank requested the collateral conversion at 03:00 PM, Ward could not produce the securities. The firm collapsed with $14 million in liabilities.
5. The Contagion: Marine National Bank failed immediately, triggering an acute panic across Wall Street, the failure of ten other financial institutions, and emergency interventions by the New York Clearing House.
The 1884 panic led directly to strict regulatory restrictions on uncollateralized bank lending to securities brokers and accelerated the creation of modern Delivery-versus-Payment (DvP) central clearing depositories.
Frequently Asked Questions (FAQ)
Why would a commercial bank issue an uncollateralized loan to a broker?
Commercial banks extend day loans because the broker-dealer is a long-standing, prime institutional client generating millions in custodial fees, foreign exchange spreads, and cash deposit balances. The bank’s risk is mitigated by strict internal credit caps, continuous monitoring of the broker’s real-time settlement queues at the DTCC, and the legal understanding that the securities delivered will immediately be pledged to secure the loan by market close.
What is the difference between a Day Loan and a Call Loan?
A day loan is strictly an intraday, unsecured facility that exists only between morning market open and afternoon market close. It requires zero physical collateral upfront. A call loan is an overnight, fully secured loan backed by liquid stocks and bonds pledged as collateral, which can remain outstanding for weeks or months, repayable whenever the bank demands (“calls”) repayment.
How do modern Central Securities Depositories (like DTCC) minimize the need for day loans?
In 19th- and 20th-century finance, day loans were mandatory because messengers physically carried paper stock certificates between bank vaults and broker offices. Modern Central Securities Depositories (such as the DTC in the US and CREST in the UK) have automated this process through Continuous Net Settlement (CNS) and real-time Delivery versus Payment (DvP). By multilaterally netting offsetting trades and executing cash debits simultaneously with electronic security credits, the intraday cash funding required by brokerages is compressed by more than 95%.
Ready to trade forex?
Open a free demo account with a regulated broker. Practice with virtual funds before risking real money.