Money Supply
Money supply refers to the total stock of currency, liquid deposits, and financial instruments circulating throughout a national economy at a given time, categorized into standardized monetary aggregates (M0, M1, M2, and M3).
What Is Money Supply?
The money supply (also referred to as monetary aggregates) is the total volume of liquid financial assets—encompassing physical cash, checking account balances, savings deposits, and near-money instruments—held by the public, non-bank businesses, and institutions across an economy at any given point in time.
Monitored and published by sovereign central banks (such as the Federal Reserve’s H.6 statistical release or the European Central Bank’s monetary bulletin), the money supply is the fundamental lifeblood of economic activity. It dictates the availability of credit, influences market interest rates, determines aggregate demand, and, according to monetary economics, serves as the ultimate structural driver of long-term price levels and consumer price inflation.
Because the forms of money range from physical banknotes in wallets to institutional repurchase agreements, central banks classify the money supply into escalating tiers based on liquidity and spendability, conventionally designated as M0, M1, M2, and M3.
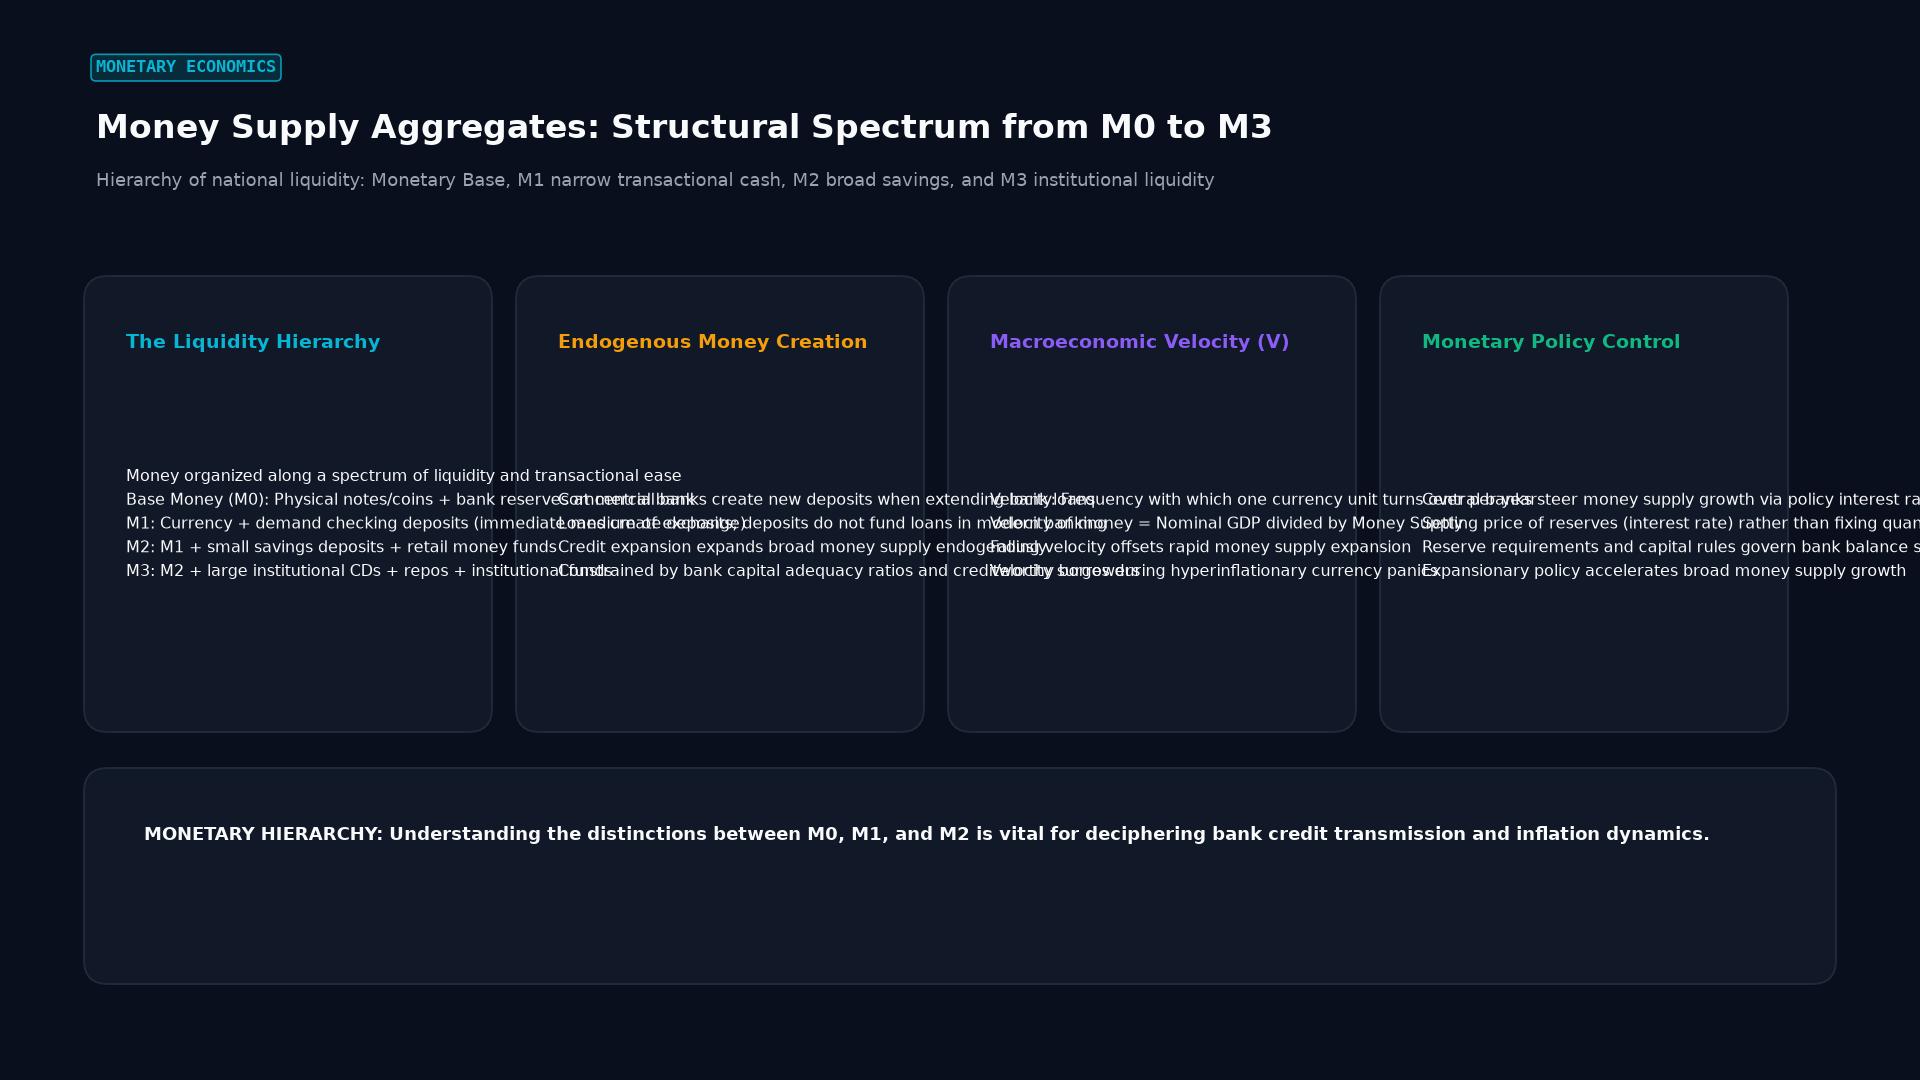 Figure: Hierarchy of national liquidity: Monetary Base, M1 narrow transactional cash, M2 broad savings, and M3 institutional liquidity
Key Takeaways
- The Monetary Hierarchy: Classified from narrowest to broadest: M0 (monetary base), M1 (demand cash/checking), M2 (broad household money), and M3 (institutional credit and deposits).
- Commercial Bank Credit Creation: While central banks control the base ($M_0$), the vast majority of broad money ($M_2$) is created organically by private commercial banks through credit extension (“loans create deposits”).
- Inflation Correlation: A persistent expansion of broad money supply ($M_2$) exceeding the productive capacity growth of an economy is the primary historical catalyst for structural consumer price inflation.
- Velocity of Money: The economic impact of the money supply depends on its velocity ($V$)—how many times an average currency unit changes hands annually to buy finished goods.
- Forex Macro Driver: Relative divergence in money supply growth between two nations is a primary determinant of long-term Purchasing Power Parity (PPP) and structural exchange rate trends.
Comparative Taxonomy: Monetary Aggregates Breakdown
| Aggregate Tier | Technical Designation | Assets Included | Primary Economic Function | Scrutiny by Central Banks |
|---|---|---|---|---|
| M0 | Base Money | Physical coins, paper currency, commercial bank reserves | Legal finality, interbank clearing collateral | Direct operational balance-sheet control |
| M1 | Narrow Money | Currency in circulation + Demand checking deposits | Immediate transaction medium for consumer purchases | Tracked for day-to-day liquidity demand |
| M2 | Broad Money | M1 + Savings deposits + Small time deposits (CDs) + Retail money market funds | Core measure of total household purchasing power | Primary indicator for inflation forecasting |
| M3 / M4 | Broadest Money | M2 + Large institutional time deposits + Repos + Eurodollars | Wholesale corporate and institutional liquidity | Discontinued by U.S. Fed in 2006; maintained in EU/UK |
The Mathematics of Money Supply and Velocity
The fundamental macroeconomic relationship governing money supply is the Quantity Theory Equation of Exchange:
$$M \cdot V = P \cdot Y$$
Where:
- $M$ is the money supply (typically M2).
- $V$ is the velocity of money.
- $P$ is the general price level (GDP deflator / CPI).
- $Y$ is real economic output (Real GDP).
The Velocity of Money is mathematically derived as:
$$V = \frac{\text{Nominal GDP}}{M_2} = \frac{P \times Y}{M_2}$$
Analytical Macro Scenarios:
- The Inflationary Surge: If money supply ($M$) surges by 25% while real economic output ($Y$) can only expand by 2%, and velocity ($V$) remains stable, price levels ($P$) must mathematically rise by approximately 23% to clear the equation.
- The Liquidity Trap: If the central bank floods the financial system with money ($M$ surges), but public uncertainty causes businesses and households to hoard cash rather than spending it, velocity ($V$) collapses symmetrically, resulting in minimal economic growth or consumer price inflation.
Real-World Case Study: The 2020 Pandemic M2 Expansion and 2022 Inflation
The COVID-19 pandemic provided the most extreme real-world demonstration of modern money supply dynamics in financial history.
- The Unprecedented Expansion: In response to lockdowns in March 2020, the U.S. Federal Reserve unleashed multi-trillion-dollar Quantitative Easing while the U.S. government issued massive direct stimulus payments.
- The M2 Spike: Between February 2020 and February 2021, U.S. M2 money supply surged by an astounding 27.1% YoY—the fastest annualized expansion since World War II.
- The Transmission: Unlike 2008 (where liquidity stayed trapped on commercial bank balance sheets), 2020 stimulus was deposited directly into consumer bank accounts (M1/M2).
- The Inflation Reality: By late 2021 and early 2022, as economic activity normalized, this massive overhang of circulating money chased constrained global supply chains, driving U.S. CPI inflation to a 40-year peak of 9.1% in June 2022.
- The Quantitative Tightening Reversal: The Federal Reserve was forced to aggressively hike interest rates by 525 basis points, causing U.S. M2 to contract year-over-year in 2023 for the first time in nearly a century.
Foreign Exchange (Forex) Valuation Transmission
Forex macro desks evaluate relative money supply trends to establish structural multi-quarter currency trends:
- Relative Monetary Growth: If Country A expands its M2 money supply by 15% while Country B expands M2 by only 3%, Country A’s currency is experiencing substantial domestic dilution.
- Interest Rate Reaction: While an initial money supply surge weakens a currency, the resulting inflation eventually forces the central bank to embark on aggressive interest rate hikes, which can subsequently trigger a fierce currency rally as global capital seeks high nominal bond yields.
Frequently Asked Questions (FAQ)
Why did the Federal Reserve stop tracking M3 in 2006?
In March 2006, the Federal Reserve discontinued publishing M3, stating that tracking large institutional deposits and repos did not provide additional non-redundant information regarding economic activity beyond what was already captured by M2, and that the administrative costs of collection outweighed the policy benefits.
Can a decrease in money supply cause a recession?
Yes. A contraction in the money supply (negative M2 growth) reduces credit availability and drains bank liquidity. Businesses face higher borrowing costs and reduced consumer demand, which historically frequently precipitates economic deceleration or recessions.
How does money supply affect stock and crypto markets?
Asset prices exhibit an extraordinarily high positive correlation with global M2 liquidity. When central banks expand the money supply, excess liquidity flows into risk assets—driving stock valuations, real estate, and cryptocurrencies to new highs. Conversely, when money supply contracts, asset multiples compress.
Ready to trade forex?
Open a free demo account with a regulated broker. Practice with virtual funds before risking real money.